Separate Bank Accounts for Taxes and Profit: Start With Three, Not Five
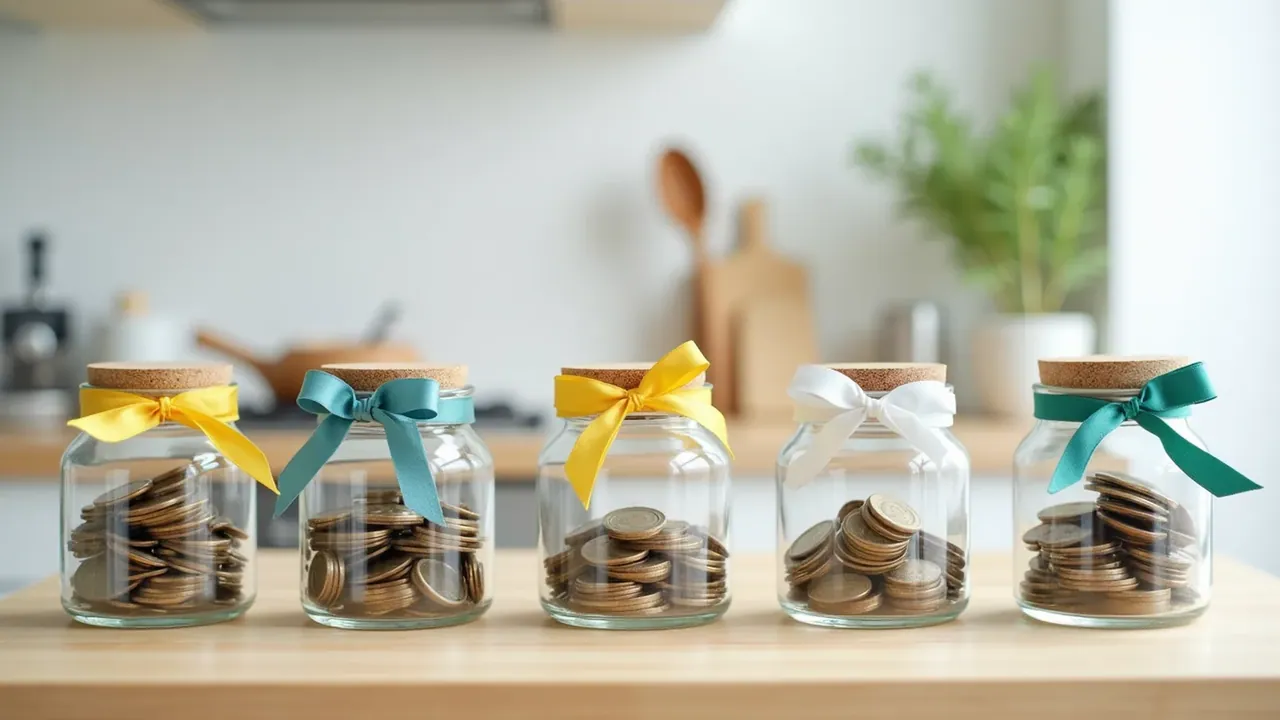
Five accounts can feel like a lot for one person. Three is enough to start, as long as each has exactly one job and a name that says what it is.
Video version: The three-account setup for freelancers
Coming soon. Everything in the video is in the written guide below.
Separate bank accounts for taxes and profit work because each balance has one job, so you can read it at a glance. You do not need five on day one. Start with three: an Income Hub where client money lands, a card-free Tax Pot, and your personal account. Add a profit account once sorting is a habit.
"Everything lands in one account, so I never know how much of it is really mine."
The confusion usually hits when you open the banking app late in the evening, see a healthy number and still cannot say whether you can afford anything.
Separate buckets where each balance tells the truth about one job. You look at your personal account and know the whole of it is yours to spend.
General information only, not financial advice. Check fees, protections and access rules before opening any account.
Why one balance hides three different truths
A single account mixes money that belongs to the tax authority, money your business needs next month and money that is genuinely yours. The total is real, but it answers none of the questions you actually ask.
That is why a $9,200 balance can feel like both a lot and nothing. The pillar on Profit First for freelancers explains the full five-bucket version. Many people read it, open too many accounts at once and give up by month two. This post is the smaller first step that tends to stick.
The three-account starting setup
| Account | Its one job | Name it |
|---|---|---|
| Income Hub | Receives every client payment. Nothing is spent from it. | "Hub: sort me" |
| Tax Pot | Holds your tax share until the bill is due. No card. | "Tax: not mine" |
| Personal account | Receives your pay. Everything in it is yours. | Your usual account |
Money flows one way: clients pay the Hub, the Hub sends tax to the Tax Pot and pay to you, and the Hub goes back to near zero. Business costs can sit in the Hub for now.
Set up separate bank accounts for taxes and profit in an evening
- Open a new account or sub-account to be your Income Hub, and update the bank details on your invoices.
- Open a Tax Pot, ideally at a different bank, and do not request a card for it.
- Name each account by its job so the name nudges you every time you log in.
- Pick two fixed sorting days a month, such as the 10th and 25th.
- On each sorting day, move your tax share to the Tax Pot and your pay to your personal account.
- After three months of steady sorting, add a Profit account and start at 1 or 2 percent.
Why the Tax Pot lives elsewhere
A Tax Pot in the same app as your spending is one swipe from being borrowed. A second bank adds a day of friction. That small delay is often enough to stop a "temporary" transfer you would regret in January.
What a sorting day looks like
A sorting day takes ten to fifteen minutes. Open the Hub, note what arrived, move the tax percentage, move your pay, and leave enough for business costs. Write the amounts in a note. Done.
Ines stops guessing her balance
Ines, 34, is a freelance illustrator who kept everything in one account. On a Sunday she opened a Hub sub-account at her usual bank and a Tax Pot at a second bank, with no card. She named them "Hub: sort me" and "Tax: not mine". On the 10th, the Hub held $6,400. She moved 27 percent, $1,728, to tax, and $3,500 to her personal account, leaving $1,172 for costs. For the first time she could look at her personal balance and know every dollar was hers. Three months later she added "Profit: keep" at 2 percent. Illustrative figures only.
The note to update your invoice details
When you change the account clients pay into, send a short, clear note. Changes to bank details can look like fraud, so tell clients in a way they can verify.
Hi [name], a quick admin note: from [date], my bank details for invoices are changing to [bank, account name]. Your next invoice will show the new details. If you'd like to confirm, please call me on the number you already have for me rather than replying to this email. Thanks, [your name]
Common setup mistakes
- Opening five accounts at once. It feels thorough and becomes a chore. Start with three and add one at a time.
- Giving the Tax Pot a card. A card turns a savings account into a spending account. Leave it off.
- Vague names. "Savings 2" tells you nothing. Name every account by what it is for.
- Sorting whenever you remember. Without fixed days, the Hub fills up and becomes a second spending account.
- Spending straight from the Hub. If you pay personal costs from it, the one-way flow breaks. Pay yourself, then spend.
When to add the next accounts
Once three accounts have run smoothly for a few months, add a Profit account. After that, a separate account for business running costs, then a salary buffer. The post on how much you should pay yourself as a freelancer explains the buffer that turns sorting days into a steady salary.
If you have borrowed from tax savings before, the review in the post on how to never be surprised by a tax bill again helps find out why.
- Every client now pays into the Hub, not your personal account.
- The Tax Pot has no card and sits at a different bank.
- You have sorted on both sorting days for the last two months.
- You can say what your personal balance is for without doing any maths.
- If the Hub keeps building up, set a calendar alert for your sorting days, and keep the routine to fifteen minutes.
The free 30-Minute Money Reset walks you through the first three-way split with your next payment.
Key takeaways
- One account hides tax, business and personal money in a single number.
- Start with three accounts: Income Hub, card-free Tax Pot, personal.
- Name each account by its job and sort on two fixed days a month.
- Add profit and other buckets only once the first three are routine.
Questions people ask
Do freelancers need separate bank accounts for taxes?
It is not usually a legal requirement for sole traders, but many freelancers find it one of the most useful changes they make. When tax money sits in your everyday account, your balance looks bigger than it really is. A separate account for tax, ideally without a card, keeps that money out of sight until the bill is due.
How many bank accounts does a freelancer need?
Three is a practical starting point: one where client money lands, one for tax, and your personal account for your pay. Many people later add accounts for profit, business running costs or a salary buffer. Start with the minimum you will actually use, then add one at a time once sorting has become routine.
Can I use sub-accounts instead of separate banks?
Yes. Many banks offer free sub-accounts or pots in the same app, which makes setup quick. The trade-off is that money in a sub-account is very easy to move back. Some freelancers keep everything at one bank except the tax account, which they hold elsewhere so that borrowing from it takes a little more effort.
Is Profit First too complicated for one person?
The full method uses several accounts and can feel heavy at first. You do not need all of it on day one. The core idea is simple: take tax and profit out first, and live on the rest. A three-account version captures most of the benefit, and you can grow into the rest later if it helps.
Not financial or tax advice
FreelancerSave is educational and is not financial, tax, legal or investment advice. Tax rates and percentages are examples only; your real figures depend on your country, income and situation, so confirm them with an accountant or your tax authority. Examples are composites and results vary. Read the full disclaimer.

Free starter kit
Make your first three-way split tonight
In 30 minutes you finish with your real Minimum Month number, a tax set-aside percentage, a separate Tax Pot account and your first three-way money split.